This article takes a lot of space to say what I've been saying for a while: The stock market is not logical. Therefore, don't try to apply logic.
Tuesday, February 22, 2011

Friday, February 4, 2011
Fannie & Freddie
About 2 weeks late, but I finally bought Fannie Mae and Freddie Mac. As I've mentioned, they were both on my watch list when they were in the $.30/share range. I bought at $.86/share and $.90/share because I still feel like they are going to hit $30-50/share. To repeat, the reason I'm interested in them is because they were $30/share 2 years ago before the meltdown, and backed by the government. They are STILL BACKED BY THE GOVERNMENT. 'nuff said.
Monday, January 31, 2011
Missed Opportunity
Friday sucked. I got my butt kicked good by the market, and I realized that Freddie Mac and Fannie Mae both had doubled from about $.30/share to $.60/share over the last few weeks. Unfortunately, I don't have free cash flow to take advantage of them. I covered investing for non-investors in my podcast over the weekend. Felt good to talk about something positive.
Anyway, tasting the can of whup @$$ that was Friday and not panicking made me feel good. Today the market was up a bit, not nearly as bad as it was down Friday, but up is still up. I feel like I just need to sit tight and I should be back where I was within a few weeks. Maybe even days. There's some serious upheaval in Egypt right now, and as is the norm, flatulence anywhere in the world is enough reason for all the investment pundits to predict that there will be a massive stink in the US market. Weeee....
Anyway, tasting the can of whup @$$ that was Friday and not panicking made me feel good. Today the market was up a bit, not nearly as bad as it was down Friday, but up is still up. I feel like I just need to sit tight and I should be back where I was within a few weeks. Maybe even days. There's some serious upheaval in Egypt right now, and as is the norm, flatulence anywhere in the world is enough reason for all the investment pundits to predict that there will be a massive stink in the US market. Weeee....
Monday, January 17, 2011
Flush the old rules down the toilet...
Remember the old days, when conventional wisdom said put away 6 months of expenses for a rainy day? Yeah, I know, it seems so quaint now. I know people who have been out of work longer than six months. Much longer. Like the 6 month mark flew by so fast their heads are spinning. Here's the new conventional wisdom for those who are temporarily in job transition:
1. Save. Don't stop at 5% of your salary, save as much as you can. I'm not saying you should live as a miser or a hermit in a cave, although that's not the worst idea in the world. Don't listen to the economists tell you that you must spend to get the economy moving again. Screw the economy, it screwed you. Get your financial house in order. Don't listen to the commercials tell you "It's time to move about the country." It's time to look after you and your family. Don't try to put 6 months of expenses away, shoot for 6 years.
2. Learn to invest your savings in investments that you feel comfortable with. Not savings, investments. Why? Because banks are giving you 1-2% return on your savings account while making 10 to 20 times that on your money. My investment of choice is the stock market. But that's me. You choose whatever you want, but take the time to understand it. Don't invest in willy or nilly. Again, understand it, but only invest what you can feel comfortable losing. Read this blog, go to the library, Google the heck out of your browser, but learn what you need to learn. It's not rocket science. Only rocket science is rocket science.
3. Coupons. Use them. They are free money and the publishers of them count on you not using them. It's like if Superbowl tickets were going $3,000 each, but some agent was selling them for $2,000 because he knows no one is going to take advantage of it, he can continue to offer them at that price. And brag about it. The manufacturers know that probably >95% of people will ignore them, so they can offer really great deals. Take them up on it.
4. Wants vs needs. That 42" LCD looks awesome when they cut off your Comcast NFL package, doesn't it? My point is, as you go through life, look at those things that you need, versus those things that you want. Stop keeping up with the Joneses. They probably lost their jobs too. And their LCDs. And their furniture. And their cars. Want to keep up with the Joneses? Go down to the unemployment office, they're probably their in line.
1. Save. Don't stop at 5% of your salary, save as much as you can. I'm not saying you should live as a miser or a hermit in a cave, although that's not the worst idea in the world. Don't listen to the economists tell you that you must spend to get the economy moving again. Screw the economy, it screwed you. Get your financial house in order. Don't listen to the commercials tell you "It's time to move about the country." It's time to look after you and your family. Don't try to put 6 months of expenses away, shoot for 6 years.
2. Learn to invest your savings in investments that you feel comfortable with. Not savings, investments. Why? Because banks are giving you 1-2% return on your savings account while making 10 to 20 times that on your money. My investment of choice is the stock market. But that's me. You choose whatever you want, but take the time to understand it. Don't invest in willy or nilly. Again, understand it, but only invest what you can feel comfortable losing. Read this blog, go to the library, Google the heck out of your browser, but learn what you need to learn. It's not rocket science. Only rocket science is rocket science.
3. Coupons. Use them. They are free money and the publishers of them count on you not using them. It's like if Superbowl tickets were going $3,000 each, but some agent was selling them for $2,000 because he knows no one is going to take advantage of it, he can continue to offer them at that price. And brag about it. The manufacturers know that probably >95% of people will ignore them, so they can offer really great deals. Take them up on it.
4. Wants vs needs. That 42" LCD looks awesome when they cut off your Comcast NFL package, doesn't it? My point is, as you go through life, look at those things that you need, versus those things that you want. Stop keeping up with the Joneses. They probably lost their jobs too. And their LCDs. And their furniture. And their cars. Want to keep up with the Joneses? Go down to the unemployment office, they're probably their in line.
Thursday, November 4, 2010
What is the Correct Stock Price?
How is a stock's price determined? I looked at SmartMoney.com's price evaluator and here's the definition: "Our Price Check Calculator can help you estimate a fair price to pay for a stock based on three main things: the company's earnings, the rate at which those earnings are projected to grow and the stock's volatility." So, it's determined using earnings, projected earnings growth rate, volatility. I also looked at MoneyChimp and they had a formula I got lost in. I went to Wikipedia and found this for the P/E ratio, just part of what goes into determining a stock's price:
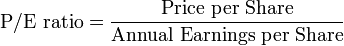

I went through all that for a reason. The pieces of each formula are reported quarterly. So if either of these is the "correct" formula for determining stock prices, why do stocks fluctuate by the minute? For example, if the formula was A x B + C/(DxE) = T, if A thru E don't change, then T should not change, right? What if T constantly fluctuates? That would mean the formula must be wrong. I think the very smart people that came up with these formulas were trying to get close to actual price of a stock, using all known current information, and they explain their misses as buying opportunities (the stock is priced lower than the formula determines) or buying at a premium (the stock is priced higher than the formula determines).
Here's a very loose example. Say I decide I want a way to predict/estimate how heavy passenger vehicles are that come down a certain road. I assume a certain load per vehicle based on the tire size and multiply by 4. Later, when I check my results against the actual, I find that sometimes my results are too high, sometimes too low. So I decide that the formula is right, the tires are over or underinflated. The problem is not with my formula, reality is wrong. Yeah, that makes all the sense in the world. But that's the equivalent of what's being said when the experts say a stock is over priced or under priced based on the assets of the company, projected sales, etc. The price of the stock reflects what someone is willing to pay for it at that moment. Period.
Speaking of charts, I put the following chart together comparing the prices of all my holdings since the beginning of the year. I haven't held each of them that long, but I wanted to see in general which way my portfolio was heading. What this tells me is that, with few exceptions, my portfolio, and probably the market in general has been headed up most of the year. I think we're probably about to have a good run for maybe the next year or two. Fortunately I'm in the game.

Thursday, October 21, 2010
3 Cheers for Netflix
As mentioned, I bought this stock a few weeks ago when Blockbuster filed for bankruptcy - and only for that reason. Netflix (NFLX) rose 13% today. Not this week. TODAY! All I can say is wow. Didn't see that coming, but happy I was standing in front of the train when it did. Coincidently, their website went down today too. What caused the gain? They had 3rd quarter earnings rise 26%. Still, that's crazy. But I'm glad to be on that side of crazy. Still keeping my eye on Fannie Mae and Freddie Mac. They're up to $.40/share each, but I don't think they're going to stay there long. I see $.30/share in their futures. When/if they get back down there, I'll consider buying them again. Why? Because they are still backed by the government and they recently sold at $60/share. As The Terminator said, they'll be back....
Wednesday, October 20, 2010
Just call me butter...
'cause I'm on a roll. Seriously, my portfolio's doing great at the moment. I have to seriously look at taking some profits off the table.
I came across this USAToday article today about the risk and reward of investing in a stock, specifically Apple. With all do respect to the author, I just don't think all of this is necessary. They talk about the compounded rate of return, "Apple's trading history back to 1984, we see the company generated an average annual compound rate of return of 31.7%". That's all well and good, but right above that the article says "Shares of the company are up 49% this year,". That to me is more important than what they were doing back in 1984. I've been a follower of Apple since about 1990. They were a totally different company in 1990 and 1984. Steve Jobs was there, then he left, now he's back. I don't see the value in tracking what they did the last 25 years. Let me move on.
The article says "To get that much better return, you had to take a lot of risk. You accepted risk — standard deviation — of 69 percentage points. So, by investing in Apple, you took on 341% more risk to get a 213% higher return." I don't even know what they're talking about. "Measure the stock's discounted cash flow." Again, huh? Apple had a butt kicking quarter - again - and they've got about $40 billion in the bank. Next.
"Compare the stock's current valuation to its historical range. BetterInvesting's Stock Selection Guide can help. If the company can increase earnings more than 18.1% a year the next five years, as analysts expect, that would put the stock in the "buy" range. " Um, they just rolled out a new Macbook Air, they have Mac OS X Lion coming out next summer, the iPhone may be rolling over to a new provider in the states come Christmas, the iPad is running out of stores... Need I say more?
Finally, the article says " An old adage on Wall Street is that the crowd is usually wrong. But Apple continues to disprove just about every tenet of investing, as the crowd has been continuously right on this one." Sooo, all the stuff you wrote in the article is bullpucky? Again, I think the only people who are worried about measuring risk, compound rate of return and increased earnings over the next 5 years are "the experts". My portfolio is up 49% since last year and over 100% the last 2 months. And I have no clue what the 25 year chart looks like for anything I own. 'nuff said
I came across this USAToday article today about the risk and reward of investing in a stock, specifically Apple. With all do respect to the author, I just don't think all of this is necessary. They talk about the compounded rate of return, "Apple's trading history back to 1984, we see the company generated an average annual compound rate of return of 31.7%". That's all well and good, but right above that the article says "Shares of the company are up 49% this year,". That to me is more important than what they were doing back in 1984. I've been a follower of Apple since about 1990. They were a totally different company in 1990 and 1984. Steve Jobs was there, then he left, now he's back. I don't see the value in tracking what they did the last 25 years. Let me move on.
The article says "To get that much better return, you had to take a lot of risk. You accepted risk — standard deviation — of 69 percentage points. So, by investing in Apple, you took on 341% more risk to get a 213% higher return." I don't even know what they're talking about. "Measure the stock's discounted cash flow." Again, huh? Apple had a butt kicking quarter - again - and they've got about $40 billion in the bank. Next.
"Compare the stock's current valuation to its historical range. BetterInvesting's Stock Selection Guide can help. If the company can increase earnings more than 18.1% a year the next five years, as analysts expect, that would put the stock in the "buy" range. " Um, they just rolled out a new Macbook Air, they have Mac OS X Lion coming out next summer, the iPhone may be rolling over to a new provider in the states come Christmas, the iPad is running out of stores... Need I say more?
Finally, the article says " An old adage on Wall Street is that the crowd is usually wrong. But Apple continues to disprove just about every tenet of investing, as the crowd has been continuously right on this one." Sooo, all the stuff you wrote in the article is bullpucky? Again, I think the only people who are worried about measuring risk, compound rate of return and increased earnings over the next 5 years are "the experts". My portfolio is up 49% since last year and over 100% the last 2 months. And I have no clue what the 25 year chart looks like for anything I own. 'nuff said
Tuesday, October 12, 2010
Blockbuster Busted...
Last week Blockbuster, after months (maybe years) of speculation, filed for bankruptcy protection. I had a buddy who managed a local branch and years ago he told me they'd spent some money to get into online streaming of movies, but after a year, decided to get out. Basically, they didn't have a clue. So I bought the combustion engine to their horse and buggy: Netflix (NFLX). I think I used to own this stock a few years ago when it was about $40/share but I got out. It's now $155/share and I'm kicking myself. No worries, it's showing up on lots of other devises like XBox and iPad, so I think it's got some more legs in it.
Still keeping an eye on Fannie Mae and Freddie Mac, and they're still selling for $.29 and $.30 a share. Anyway, I'm doing pretty well. My prediction that the market would hit 10,000 before 11,000 was waaaayyy off. My big winner today is Starbucks, it's up 4% because some analysts suddenly have "more confidence" in the company. Last month they said they were raising prices.
Here's my current holdings and returns as of close today:
Still keeping an eye on Fannie Mae and Freddie Mac, and they're still selling for $.29 and $.30 a share. Anyway, I'm doing pretty well. My prediction that the market would hit 10,000 before 11,000 was waaaayyy off. My big winner today is Starbucks, it's up 4% because some analysts suddenly have "more confidence" in the company. Last month they said they were raising prices.
Here's my current holdings and returns as of close today:
| AAPL | 178.72% |
| AET | 1.67% |
| AGP | 50.94% |
| AIG | 12.10% |
| AXP | 186.36% |
| BP | 7.29% |
| COF | 2.89% |
| DIS | 34.65% |
| EBAY | 16.12% |
| F | 223.65% |
| JBLU | 12.91% |
| LF | 3.95% |
| LVLT | -30.94% |
| MA | 33.89% |
| NFLX | 0.35% |
| PG | -5.67% |
| SBUX | 35.70% |
| SIRI | 17.39% |
| TJX | -0.22% |
| TM | -8.81% |
| XRX | 65.24% |
Sunday, September 26, 2010
They really don't know what they're talking about!
When I started this blog, part of the reason was because I was doing is because after the financial meltdown it confirmed to me that making my own decisions was the best way to do. Sure, I may miss out on some great runs, but I also haven't lost several BILLION dollars. The question that keeps coming up is how did they lose so much money? Simple, THEY DIDN'T KNOW WHAT THEY ARE DOING!
First, here's the Cliff Notes version of what happened when the whole financial world went crazy:
That's the truly Cliff Noted version of the mess. For a more detailed and entertaining summary, read Michael Lewis's The Big Short: Inside The Doomsday Machine. I recently heard Mr. Lewis in an interview on NPRs Wait Wait Don't Tell Me game show. The one thing he reiterated is that Wall Street still doesn't have a clue. (Read his book Liar's Poker for a more in depth discussion of Wall Street's cluelessness.)
I guess the long overdue point I'm making is, why would anyone blindly trust their future to an industry that does not have anywhere near your best interest at heart and take their fees up front whether they actually make you money or not? Trust me, investing in stocks and bonds is not rocket science So long as they make you believe 1) it's too hard to do on your own and 2) they know what they're talking about, they have you.
Before I get beat up, I have no ax to grind with financial advisors or investment bankers. I just think that those "experts" on Wall Street that almost destroyed the economy of the planet are probably as collectively stupid as they appear.
As for me, my portfolio has been on a roll as of late. My return has doubled in the last month. Still looking at Fanny Mae and Freddie Mac, they're still under $.30 a share so I'm still watching it.
First, here's the Cliff Notes version of what happened when the whole financial world went crazy:
- People were being given fixed and adjustable rate mortgages they absolutely could not afford (yours truly included). In some cases, the person getting the mortgage didn't have to verify that they even had a job. They figured they could always sell the house at a higher price and make money. Remember all those house flipping shows on A&E on Saturday mornings?
- Because so much money was so easily available, housing prices kept increasing. This is what was known as the housing bubble. (um, bubbles pop..)
- These mortgages were grouped together and sold to investors as a big block of A-rated assets. Why? Because the rating agencies and the financial institutions selling them did not actually look at the individual mortgages that were making up the blocks. They kinda sorta took each other's word that it was all good. They then borrowed money, using these "assets" as collateral.
- It's more complicated, but some people looked into the blocks and realized what a mucking fess they were. They then made bets against the assets, realizing they were eventually going to blow up. It got so crazy that some fund managers were having blocks put together that were as bad as they could make them, sell them to their clients, then bet against the same block they told their clients were rock solid. These were all still getting A-ratings.
- Eventually, when the adjustable mortgages reset to their final rate the mortgage payments shot up, much higher than the mortgagee could afford. And the fixed rate mortgagees couldn't sell the house they shouldn't have bought anyway, nor could they afford the payments. As a result, a few new things happened:
- Housing prices stopped rising because there were no new people to get ridiculous mortgages. For more info, take a look at Tulipmania.
- Mortgagees started defaulting like crazy because they couldn't afford the payments.
- Because the mortgages started defaulting, the blocks of mortgages lost value. Remember these blocks were used as collateral for loans. If suddenly you don't have collateral, your loan can get called in. If you don't have the money to replace the lost value, screwed is an understatement. By the time the mortgages were defaulting and taking the investors with them, Wall Street had been buying each other's crappy crap crap, so when one went over the cliff, they were all handcuffed together and they all went.
That's the truly Cliff Noted version of the mess. For a more detailed and entertaining summary, read Michael Lewis's The Big Short: Inside The Doomsday Machine. I recently heard Mr. Lewis in an interview on NPRs Wait Wait Don't Tell Me game show. The one thing he reiterated is that Wall Street still doesn't have a clue. (Read his book Liar's Poker for a more in depth discussion of Wall Street's cluelessness.)
I guess the long overdue point I'm making is, why would anyone blindly trust their future to an industry that does not have anywhere near your best interest at heart and take their fees up front whether they actually make you money or not? Trust me, investing in stocks and bonds is not rocket science So long as they make you believe 1) it's too hard to do on your own and 2) they know what they're talking about, they have you.
Before I get beat up, I have no ax to grind with financial advisors or investment bankers. I just think that those "experts" on Wall Street that almost destroyed the economy of the planet are probably as collectively stupid as they appear.
As for me, my portfolio has been on a roll as of late. My return has doubled in the last month. Still looking at Fanny Mae and Freddie Mac, they're still under $.30 a share so I'm still watching it.
Monday, September 20, 2010
The Recovery
Since my last post, I've done pretty well, actually more than doubled my gains. Still, I'm bearing on "the market" even if "my market" is doing great. Today the market stands about 10,700. I still think it will hit 10,000 before 11,000. Why? I just see this market as still pretty skiddish. I got rid of Freddie Mac (FMCC.OB) & Fannie Mae (FNMA.OB) and they are still tanking. I still plan to jump back into them when they look like they're going to recover.
A few months back, the markets went buck nutty because of the collapse of the Greek economy. While I still don't know why my stocks got hit because of it, there is a very good NPR podcast called Planet Money that explains exactly what mess Greece got itself into.
The problem I will have soon if this market keeps going like it is, is when do I get out? Here's my holdings and current gains & losses.
I'm approaching my alltime high in dollars and will start paring down soon. Stay tuned...
A few months back, the markets went buck nutty because of the collapse of the Greek economy. While I still don't know why my stocks got hit because of it, there is a very good NPR podcast called Planet Money that explains exactly what mess Greece got itself into.
The problem I will have soon if this market keeps going like it is, is when do I get out? Here's my holdings and current gains & losses.
| AAPL | 163.44% |
| AET | -0.13% |
| AGP | 34.75% |
| AIG | -1.74% |
| AXP | 219.72% |
| BP | 0.39% |
| COF | -0.23% |
| DIS | 35.97% |
| EBAY | 16.08% |
| F | 194.85% |
| JBLU | 2.44% |
| LF | -5.06% |
| LVLT | -19.69% |
| MA | 30.99% |
| PG | -6.61% |
| SBUX | 30.60% |
| SIRI | 1.74% |
| TJX | -4.53% |
| TM | -6.46% |
| XRX | 53.03% |
I'm approaching my alltime high in dollars and will start paring down soon. Stay tuned...
Monday, August 30, 2010
Bye Bye Banks
I got out of some of my banks and a telecom today, Citigroup (C), Bank of America (BAC) and Research In Motion (RIMM). They were killing my returns. I think the banks will rise at some point, but I think they will continue to fall until at least 1Q11 (first quarter 2011). As for RIMM, unless they got an answer to the iPhone, they're toast in the long term. And it's getting warm...
And looking at my holdings, I'll be pulling out of more stuff tomorrow. The "market" is hovering around 10,000. It dropped 140 points today, the big loser was Frontier Financial (FTBK.PK), losing 25% today on absolutely no good or bad news. I think the Dow will hit 9,000 before 11,000. Why? Because it is having a heck of a time holding itself above 10,000 and the economy is still stalled. Businesses aren't hiring (trust me, I know). The market has tried to lift itself for the past 6 months, but it can't sustain it. Therefore, I think 10,000 is an artificial level and it will slowly drift down over the next 4-6 months. Given that, I think some of my good holdings might have to be cut. Ironically, I'm only down 8% in AIG (AIG), the one who started this mess.
Wednesday, August 25, 2010
Run For the Hills!
Another bad day in StockMarketVille. The Dow lost 133 points, due to a huge drop in home sales, ie, "..nobody bought houses last month, I better sell all my stocks!". My big loser was Web Media Brands (WEBM), who lost 10% yesterday, they announced financials a week ago - apparently it took everyone a week to read them. They did announce a smartphone games summit yesterday. I guess nobody wants to go. No, I don't see a correlation between smartphones and home sales either.
As we get toward the end of the year, I think mutual fund managers will start trying to clean up their holdings so when they report out in December they don't have all that crap they been losing money on all year on their books. That and the housing news will make for an ugly time ahead, at least until the mid term elections in November. In my logic, that will put downward pressure across the board. I see the downside a higher likelihood than the upside, at least for a few months. I'm not going to sell everything, but I'm going to take a good hard look at RIM, Yahoo and a few of the bank stocks I'm holding and been getting my butt kicked on. I'm not making any predictions on what I think these companies will do, but I don't see their stocks going anywhere positive for a while. I think/hope today will make a bit of a recovery since the market has been dropping for a few days. But I don't think it will last, so I'm going to actually try to time the market this time. OK, let's be honest, we all do that but don't call it that.
Thursday, August 19, 2010
He Giveth and He Taketh
As good as the last few days were, today is worse. "The Market" is currently down about 156 points, but so are about 90% of the stocks I follow. It ended losing 144 points for the day. The "experts" are saying it's because jobless claims were announced to day and are higher than expected. Apparently, most of the people who are trading stocks (Ma and Pa Public) are sitting around waiting for bad or good news and making their immediate trading decisions based on what they hear. Here's a new one: The Hindenberg Omen! I guess if you frequently cry doom and gloom, eventually you will be right.
The big loser on my watch list is Frontier Financial (FTBK.PK) who lost 20% today. No headlines so I can't tell you what was behind it. They were followed by Motors Liquidators (MTLQQ.PK), that quasi company that sorta kinda owns GM (article), down 14.8% for the day. Bummer news since yesterday they announced they were going to push for an initial public stock offering. I haven't decided if I would buy GM in their IPO. Chances are, if you can get in good the first few days you'll make out like a bandit on speculation, just not sure if I believe they've turned themselves around sufficiently to warrant any long term consideration.
Wednesday, August 18, 2010
Fannie & Freddie and GM wants us to buy it, again
Wow. A uthentidate Holdings (ADAT), yesterday's big winner, is down 11.6% today. And still no headlines. This is a perfect example of the illogic of the stock market. Freddie Mac & Fannie Mae both got waxed. Probably had to do with "NEW YORK (Reuters) - The four largest U.S. banks could face as much as $42 billion in losses as they repurchase faulty mortgages from housing finance giants Fannie Mae and Freddie Mac, Fitch Ratings said on Wednesday." At least this time there was really something for the market to react to.
 GM filed paperwork for an initial public offering today, meaning we'll be able to buy ownership shares in the company we bought last year. I have mixed feelings about GM. I think if they go back public, in the short run at least the stock will jump. But I haven't yet seen that they are doing anything different than what they've done the last 30 years which got them into this mess in the first place.
Read an interesting article about Google. They are up almost 389% since they went public 6 years ago, but they are down 20% YTD. That means if you bought Google on January 1, 2010, you have lost 20% - on the Google! The same company that is selling Andriod cell phones all over the place. I guess the point is you can't invest in the popular companies at the wrong time.
Tuesday, August 17, 2010
Back in the saddle
My apologies to the few of you reading this. Job search has been taking all my time the last few weeks. No excuse, I need to keep writing and I will definitely try harder. Now, let's look at today's market. It's 3:05 and "the market" is up 154 points. Big whoop, what's really important to me is that my holdings are up 1.4% for the day. USAToday says that the markets are up due to rising home sales. Soooooo, because your neighbors are buying houses, you buy stocks. Sorry, that doesn't make sense to me. As time goes on, I'm thinking more and more stock transactions are computer initiated, if stock X goes up, then buy stock Y. The article also said people are encouraged by higher earnings are The Home Depot (HD) and Walmart (WMT). Here's my unbelief, for this all to be true, 100 million investors would have to be glued to their TVs looking at housing starts and big name company earnings and immediately making the decision either buy or sell a bunch of stocks all over the place.
Earlier today Authentidate Holding Corp (ADAT) was up 12% for the day. It's now up just over 2%. What was the big news that caused this spike in this company with a market capitalization of $30 million? Beats me. According to Yahoo they haven't had a headline in 12 days. They have an earnings announcement in September. But they did get a new PR firm a few weeks back. I guess it's working. As I'm writing this, it's back up 11%. My guess is that when some other stock moved some computer algorithm said buy a poopload of ADAT, now sell it, now buy it again. Seriously, imagine the people who work there and maybe have their 401ks wrapped up in this company's stock. They must be going batpoop today.
Netflix (NFLX) is down 2% today, the only news I see is that HBO is going to the iPad and not to Netflix. Theroretically, 2% of the value of Netfilx was due to an impending HBO distribution deal. Um, yeah, right. Frontier Financial got a 13% haircut today. Why? Beats me. The last headline was June 9 about a shareholder lawsuit. My point is, if it was news driving this stock down 13%, we'd know. It's not people, it's Skynet....
Oh yeah, still following Fannie Mae and Freddie Mac. They're still in the $.40 range. Haven't repulled the buy trigger yet. I think they may shrink a little more.
Wednesday, August 4, 2010
The Return of Moe
Hey, I didn't post in July, the job search has been taking all my time. I'm still out of Fannie Mae and Freddie Mac, waiting for them to finally bottom out. I still think they are great long term plays as the government still backs them.
Haven't bought or sold anything over the past 4 weeks, my returns are finally starting to look decent again. I think in general "the market" has probably bottomed out and now is a good time to snag bargains, then again, it's always a good time to snag bargains. It was a gamble, but as of today I'm still up 2% in BP (BP). I am going to keep my eye on RIM, they got smacked down today. Maybe someone besides Priceline (up 22%) had a good day, but in general the market seems to be blah today. For all the hoopla about Android phones, the Google's stock isn't moving.
Tuesday, June 29, 2010
It's an ugly world out there
The Dow dropped 268 points today - and took most of my portfolio with it. All I can say is I don't think this will be a permanent state. I have 20 years to go to retirement so I can afford to sit and wait it out. If you have money you need sooner, you have to decide what to do. One thing to consider, it's not a loss until you actually sell....
Friday, June 18, 2010
BP Rebound, Looking at Fannie Mae & Freddie Mac
It's been a decent week. I'm up about 25% v 40% a few months ago and 20% a few weeks ago. I'm still down in BP about 10%. Hearing about the $20 billion fund they're putting together for the Gulf of Mexico oil spill disaster says they're not going out of business and in a year, if not less, barring anymore SNAFUs I think they'll be right back to where they were a few months ago.
Looking at Fannie Mae (FNM) & Freddie Mac (FRE). Five years ago, Fannie Mae was selling for $70/share, Freddie Mac was selling for about $50/share. They've both been delisted by the New York Stock Exchange, because they're selling for less than a dollar a share, about $.50/share each. They are both still government sponsored enterprises, which I think means they're not going anywhere anytime soon. I'm trying to let it drop a little more, but I think I'll be buying in the next week or so.
Thursday, June 10, 2010
Finally a Good Day
Today was a good day. After a week of bad days. Very bad days. I'm still down from my high by about 50%. That translates to mean 2 months ago I was up 40% for the year, now I'm only up 21%. I'm down 15% in BP, but yesterday I was down 28%, yeah, it rose 13% in one day. Welcome to the illogic of the stock market. This in the midst of them SNAFUing the Gulf of Mexico oil spill every whichaway they can. But I stand by my thought that it is a good time to be jumping into the stock market. I'm currently reading Michael Lewis' The Big Short: Inside the Doomsday Machine. Fascinating reading. It reinforces my theory that the big brains on Wall Street are just as dumb at the rest of us.
Thursday, June 3, 2010
Why I might buy British Petroleum (BP) stock
Slowly the market is coming back, rising over 200 points yesterday. I'm still down, but having some really good days. I'm looking at British Petroleum (BP), yes the company responsible for the biggest oil spill in history. Why? Because it is getting hammered. This is where personal choice comes to play.
About 20 years ago, several financial companies started marketing mutual funds that excluded "sin" type companies like tobacco, gambling and alcohol. The goal was to attract people who had aversions to the kinds of products and services these companies sold and, therefore, would choose not to invest in them. Very valid point. If you don't agree with what a company does, you are well within your right not to invest in that company. My problem/issue with that type of investment mix is that 1) investing is about, for the most part, getting the best return, not expressing your distaste for drinking, smoking or any other questionable yet legal activities, 2) these portfolios have been put together not becauase someone did research and decided they were a good mix from an investment perspective, they were put together because they are a good mix from a marketing perspective (I don't invest in marketing) and 3) I don't care for mutual funds, see previous posts.
Getting back to my point about British Petroleum, I think they have handled this whole spill horribly, starting with before the spill. They had no plan for cleaning up a mess of this magnitude, yet they've probably thrown millions into figuring out how to drill 5 miles below the surface of the ocean. Having said all that, they are still in business. Their stock has lost about 50% of it's value in the last month, and over the last 10-15 years they have made a boatload of money. Assuming they don't get liquidated due to lawsuits (see Arthur Anderson) or taken over by a competitor, they will be back. Why? Because as George Bush said, "We are addicted to oil." and that addiction ain't going nowhere no time soon. So, yes, it's a gamble, but I can see this working out for BP such that in a year or so the stock price is right back where it was a month ago. A 100% return in 12 months ain't bad at all.
Do I feel bad about investing in a company that royally screwed up the GULF OF MEXICO for decades? Nope. If you want to get picky, go protest the people you see lined up at BP gas stations. They're the ones supporting the company, I'm just gambling.
Subscribe to:
Posts (Atom)