Thursday, September 22, 2011

The Apple of my eye & Netflix - Huh?


Caveat, I'm a big Apple fan. They just announced a press event for October 4.

The assumption is this is the new iPhone (oh please oh please oh please let it run on Sprint!). I digress.
I doubled down, buying more around the time that Steve Jobs announced he was retiring as
CEO, at around $380/share.  Today it's $419.  That's over 10%. In a month. Why, because even
without him, the company is very well run.  And I still think it's a good deal, Some things to consider:  It's the largest publicly held company in the world by market capitalization, and it doesn't have a monopoly in any segments. Including iPads as computers, it's only got about 12% of the market. But it has the vast bulk of the profits. Let me repeat that. Apple is making all the money. This year
Apple captured two thirds of available mobile phone profits in Q2.The analysts are putting prices like $500-$520/share on the stock. As I've said before, I don't believe in analysts for a few reasons, primarily, they are not inside the company, and don't have a real clue as to how the day to day operations are going, nor do they know what products might or might not be in the pipeline.  Morgan Stanley feels Apple should buy back some of it's shares, because it has too much money on hand. With all due respect to the probably very intelligent analysts at Morgan
Stanley, that's the stupidest thing I ever heard.  We're going through a recession/depression/giant suck of an economy and they're saying someone has too much cash on hand?  Really?  Hm, I bet Circuit City, Blockbuster or Borders wished they had too much cash on hand. Sometimes people talk to keep the quiet from enveloping them. I've been a shareholder for over a decade. I've never gotten a dividend, and I'm cool with it. When I originally bought the stock around $4 I didn't expect one, nor do I now. I don't want one. I want them to keep that money in the bank, keep making great stuff and keep getting more valuable. My point is, this train ain't stopping no time soon....

Netflix - Huh?

On July 23, 2011 Netflix stock hit $298/share.Today it's at $130. The stock had tripled since 2010. Well, scratch that. What happened? A couple things... They had already vanquished Blockbuster, who was too stubborn to see streaming as a viable alternative to physical stores.  So they were BMOC in video.  From everyone I talk to, the biggest problem with their streaming service is lack of popular/current titles. That isn't totally their fault, the content creators don't want movies streaming too fast, it undercuts the DVD market.  So, in the middle of all this, they are in ugly negotiations with STARZ, one of their MAJOR content providers. They double down: raising the price on streaming to current customers, even though never raising their content from suck to less suck. There's a backlash, they pretty much ignore it. Then they triple down: separating the streaming and DVDs by mail into 2 separate business units, calling the DVDs by mail Quickster. Wow. Bet that took a long meeting to come up with. The price will be the same for the combined service (the new, higher price), but now you will have 2 debits on your monthly credit card bill versus one.  Anyway, the STARZ negotiations imploded, so the library will be going from suck to more suck. And as I understand it, that's the streaming and the DVD libraries.  So more suck 2012 costs more than suck 2011. Good move. The sad thing is, there's no one to take advantage of the missteps. Blockbuster, a shell of it's former self, isn't set up to do streaming or large volume DVDs by mail. But Coinstar and Amazon, not to mention that other company, Apple's iTunes are all out there

Bottom line, I don't think Netflix is going away, but they really need to get off their act together. The stock is probably a buying opportunity right now because at $298 it was probably over rated, and at $130 it's probably under rated.

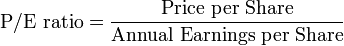


Monday, September 19, 2011

Inside Info On Why Walmart Will Eventually Fail

Before you call the authorities because I have "insider" info, I got mine the old fashioned way: I went inside a Walmart.  Let me back up. The first time I went into a Walmart was maybe 10 years ago. I was blown away.  It started with the "greeter" as you walked in, and went uphill from there.  In the last decade, I've seen the place decline.  The greeters and stores aren't as inviting, they seem to be employing some screwed up version of Just In Time Staffing, maybe based on dollars per hour wrung up or some such. Whatever they're using, it's an epic fail in my book. We have an unemployment rate around 8%, Walmart's making money, yet 99% of the time I'm at my local Walmart. no more than 4-6 of the 24 cash registers are open.  And the lines are crazy sometimes.  If it's after 11 PM or in the wee hours of the morning,  then we're talking 1 register is open.  If you go to Walmart after 11, be prepared to stand in line for 30-45 minutes.  They close the self serve lines whenever the person watching them has to go home.  My point is, and this is not just my opinion, people tolerate Walmart because they usually have the best prices. But there is going to come a point when we are going to stop tolerating it for the sake of saving a few dollars.  And yes, it is a bad omen when your customers "tolerate" you.

To be fair, I looked at Walmart's stock performance.  It hit $69/share in December 1999, and is now finally getting back to that point.  Walmart is famous for squeezing  pushing their supplies to cut costs so they can pass the savings on, but if you make enemies, you should also make friends. Walmart has annoyed it's suppliers and its customers. I'm going to keep my eye on it. If I do buy some, I'm not planning to hold it forever. I still feel like it's going to go down eventually.

Thursday, August 4, 2011

Run for the hills

A month ago, I was considering getting out of the market totally because I just had the feeling this debt ceiling mess was going to clean some clocks. Stupid me. I stayed in, and got spanked the last week. I think I'm getting out tomorrow morning. Why? Because I think the markets are at the beginning of a very slow and  a very long beat down.  I don't have any evidence, any insider info, but I think tomorrow is going to make today's 500+ point drop in the Dow look like foreplay. And if not tomorrow, next week, next month, the next 6 months are going to be ugly. I'm sitting this one out again. And when the dust settles, I'm jumping back in. Stay tuned....

Good luck....

Friday, May 6, 2011

Where did all the money go?

It's been a moment or 3 since I've written. My bad.   Anyway, I was listening to a podcast and someone asked a question, where did all the "value" go that disappeared in the stock market crash of 2008?  The truth is, it wasn't real in the first place. Let me give you an example, if you have a car you want to sell, a rare, vintage 1937 whatever. There are only 4 known in existence. It might be worth a tidy sum, say $100,000. It's worth that because that's what someone is willing to pay you for it.  You haven't sold it, that's just the going rate. That money doesn't exist in your pocket until you actually sell the car. (it's kinda like saying Mark Zuckerberg is worth x billion dollars because someone says that Facebook, a privately held company, is worth y billion dollars.)

Say one day someone finds a stash of 14 more of the exact same 1937 vintage vehicles, in a warehouse in East Bubblebutt, NJ.  Suddenly yours isn't so rare anymore. Suddenly the market of people willing to give you $100,000 for yours starts to shrink, as does the "value" of yours. Within 2-3 months, the "going price" for yours is only $60,000, because the original value was based on the rarity of it.  You lost $40,000. Or did you?  Did you physically have $40,000 4 months ago that you don't have now? No. So how did you lose it? That's what happened in the stock market. And happens everyday. The value of a stock is based on what you can get someone to give you to own it. All the daily market fluctuations are the changes in what people are willing to pay to own stock X. When they decide they don't want to own it that bad, the value decreases. It's like being the only girl at an all-boy school. Then 300 new girls enroll. Yeah, exactly.

So, where did all the money go?  Poof....

Tuesday, February 22, 2011

Like I been saying....

This article takes a lot of space to say what I've been saying for a while: The stock market is not logical. Therefore, don't try to apply logic.

Friday, February 4, 2011

Fannie & Freddie

About 2 weeks late, but I finally bought Fannie Mae and Freddie Mac. As I've mentioned, they were both on my watch list when they were in the $.30/share range. I bought at $.86/share and $.90/share because I still feel like they are going to hit $30-50/share.  To repeat, the reason I'm interested in them is because they were $30/share 2 years ago before the meltdown, and backed by the government. They are STILL BACKED BY THE GOVERNMENT. 'nuff said.

Monday, January 31, 2011

Missed Opportunity

Friday sucked. I got my butt kicked good by the market, and I realized that Freddie Mac and Fannie Mae both had doubled from about $.30/share to $.60/share over the last few weeks. Unfortunately, I don't have free cash flow to take advantage of them. I covered investing for non-investors in my podcast over the weekend.  Felt good to talk about something positive.

Anyway, tasting the can of whup @$$ that was Friday and not panicking made me feel good. Today the market was up a bit, not nearly as bad as it was down Friday, but up is still up.  I feel like I just need to sit tight and I should be back where I was within a few weeks. Maybe even days. There's some serious upheaval in Egypt right now, and as is the norm, flatulence anywhere in the world is enough reason for all the investment pundits to predict that there will be a massive stink in the US market. Weeee....

Monday, January 17, 2011

Flush the old rules down the toilet...

Remember the old days, when conventional wisdom said put away 6 months of expenses for a rainy day? Yeah, I know, it seems so quaint now. I know people who have been out of work longer than six months. Much longer. Like the 6 month mark flew by so fast their heads are spinning.  Here's the new conventional wisdom for those who are temporarily in job transition:

1. Save. Don't stop at 5% of your salary, save as much as you can. I'm not saying you should live as a miser or a hermit in a cave, although that's not the worst idea in the world. Don't listen to the economists tell you that you must spend to get the economy moving again. Screw the economy, it screwed you.  Get your financial house in order. Don't listen to the commercials tell you "It's time to move about the country." It's time to look after you and your family. Don't try to put 6 months of expenses away, shoot for 6 years.

2. Learn to invest your savings in investments that you feel comfortable with. Not savings, investments. Why? Because banks are giving you 1-2% return on your savings account while making 10 to 20 times that on your money.  My investment of choice is the stock market. But that's me. You choose whatever you want, but take the time to understand it. Don't invest in willy or nilly. Again, understand it, but only invest what you can feel comfortable losing.  Read this blog, go to the library, Google the heck out of your browser, but learn what you need to learn. It's not rocket science. Only rocket science is rocket science.

3.  Coupons. Use them. They are free money and the publishers of them count on you not using them. It's like if Superbowl tickets were going $3,000 each, but some agent was selling them for $2,000 because he knows no one is going to take advantage of it, he can continue to offer them at that price.  And brag about it.  The manufacturers know that probably >95% of people will ignore them, so they can offer really great deals. Take them up on it.

4. Wants vs needs. That 42" LCD looks awesome when they cut off your Comcast NFL package, doesn't it? My point is, as you go through life, look at those things that you need, versus those things that you want.  Stop keeping up with the Joneses. They probably lost their jobs too. And their LCDs. And their furniture. And their cars. Want to keep up with the Joneses? Go down to the unemployment office, they're probably their in line.

Thursday, November 4, 2010

What is the Correct Stock Price?

How is a stock's price determined?  I looked at SmartMoney.com's price evaluator and here's the definition: "Our Price Check Calculator can help you estimate a fair price to pay for a stock based on three main things: the company's earnings, the rate at which those earnings are projected to grow and the stock's volatility."  So, it's determined using earnings, projected earnings growth rate, volatility. I also looked at MoneyChimp and they had a formula I got lost in.  I went to Wikipedia and found this for the P/E ratio, just part of what goes into determining a stock's price:
\mbox{P/E ratio}=\frac{\mbox{Price per Share}}{\mbox{Annual Earnings per Share}}
I went through all that for a reason. The pieces of each formula are reported quarterly. So if either of these is the "correct" formula for determining stock prices, why do stocks fluctuate by the minute? For example, if the formula was A x B + C/(DxE) = T, if A thru E don't change, then T should not change, right? What if T constantly fluctuates? That would mean the formula must be wrong.  I think the very smart people that came up with these formulas were trying to get close to actual price of a stock, using all known current information, and they explain their misses as buying opportunities (the stock is priced lower than the formula determines) or buying at a premium (the stock is priced higher than the formula determines).

Here's a very loose example. Say I decide I want a way to predict/estimate how heavy passenger vehicles are that come down a certain road. I assume a certain load per vehicle based on the tire size and multiply by 4.  Later, when I check my results against the actual, I find that sometimes my results are too high, sometimes too low.  So I decide that the formula is right, the tires are over or underinflated.  The problem is not with my formula, reality is wrong.  Yeah, that makes all the sense in the world. But that's the equivalent of what's being said when the experts say a stock is over priced or under priced based on the assets of the company, projected sales, etc.  The price of the stock reflects what someone is willing to pay for it at that moment. Period.

Speaking of charts, I put the following chart together comparing the prices of all my holdings since the beginning of the year. I haven't held each of them that long, but I wanted to see in general which way my portfolio was heading.  What this tells me is that, with few exceptions, my portfolio, and probably the market in general has been headed up most of the year. I think we're probably about to have a good run for maybe the next year or two.  Fortunately I'm in the game.

Thursday, October 21, 2010

3 Cheers for Netflix

As mentioned, I bought this stock a few weeks ago when Blockbuster filed for bankruptcy - and only for that reason. Netflix (NFLX) rose 13% today. Not this week. TODAY!  All I can say is wow. Didn't see that coming, but happy I was standing in front of the train when it did.  Coincidently, their website went down today too.  What caused the gain?  They had 3rd quarter earnings rise 26%. Still, that's crazy. But I'm glad to be on that side of crazy.  Still keeping my eye on Fannie Mae and Freddie Mac. They're up to $.40/share each, but I don't think they're going to stay there long. I see $.30/share in their futures.  When/if they get back down there, I'll consider buying them again.  Why? Because they are still backed by the government and they recently sold at $60/share.  As The Terminator said, they'll be back....

Wednesday, October 20, 2010

Just call me butter...

'cause I'm on a roll. Seriously, my portfolio's doing great at the moment. I have to seriously look at taking some profits off the table. 


I came across this USAToday article today about the risk and reward of investing in a stock, specifically Apple.  With all do respect to the author, I just don't think all of this is necessary.  They talk about the compounded rate of return, "Apple's trading history back to 1984, we see the company generated an average annual compound rate of return of 31.7%".  That's all well and good, but right above that the article says "Shares of the company are up 49% this year,".  That to me is more important than what they were doing back in 1984. I've been a follower of Apple since about 1990.  They were a totally different company in 1990 and 1984. Steve Jobs was there, then he left, now he's back. I don't see the value in tracking what they did the last 25 years.  Let me move on.


The article says "To get that much better return, you had to take a lot of risk. You accepted risk — standard deviation — of 69 percentage points. So, by investing in Apple, you took on 341% more risk to get a 213% higher return."  I don't even know what they're talking about. "Measure the stock's discounted cash flow." Again, huh? Apple had a butt kicking quarter - again - and they've got about $40 billion in the bank. Next.


"Compare the stock's current valuation to its historical range. BetterInvesting's Stock Selection Guide can help. If the company can increase earnings more than 18.1% a year the next five years, as analysts expect, that would put the stock in the "buy" range. " Um, they just rolled out a new Macbook Air, they have Mac OS X Lion coming out next summer, the iPhone may be rolling over to a new provider in the states come Christmas, the iPad is running out of stores... Need I say more?


Finally, the article says " An old adage on Wall Street is that the crowd is usually wrong. But Apple continues to disprove just about every tenet of investing, as the crowd has been continuously right on this one." Sooo, all the stuff you wrote in the article is bullpucky?  Again, I think the only people who are worried about measuring risk, compound rate of return and increased earnings over the next 5 years are "the experts". My portfolio is up 49% since last year and over 100% the last 2 months. And I have no clue what the 25 year chart looks like for anything I own.  'nuff said

Tuesday, October 12, 2010

Blockbuster Busted...

Last week Blockbuster, after months (maybe years) of speculation, filed for bankruptcy protection. I had a buddy who managed a local branch and years ago he told me they'd spent some money to get into online streaming of movies, but after a year, decided to get out.  Basically, they didn't have a clue. So I bought the combustion engine to their horse and buggy: Netflix (NFLX). I think I used to own this stock a few years ago when it was about $40/share but I got out. It's now $155/share and I'm kicking myself. No worries, it's showing up on lots of other devises like XBox and iPad, so I think it's got some more legs in it.

Still keeping an eye on Fannie Mae and Freddie Mac, and they're still selling for $.29 and $.30 a share.  Anyway, I'm doing pretty well. My prediction that the market would hit 10,000 before 11,000 was waaaayyy off.  My big winner today is Starbucks, it's up 4% because some analysts suddenly have "more confidence" in the company.  Last month they said they were raising prices.

Here's my current holdings and returns as of close today:

AAPL 178.72%
AET 1.67%
AGP 50.94%
AIG 12.10%
AXP 186.36%
BP 7.29%
COF 2.89%
DIS 34.65%
EBAY 16.12%
F 223.65%
JBLU 12.91%
LF 3.95%
LVLT -30.94%
MA 33.89%
NFLX 0.35%
PG -5.67%
SBUX 35.70%
SIRI 17.39%
TJX -0.22%
TM -8.81%
XRX 65.24%

Sunday, September 26, 2010

They really don't know what they're talking about!

When I started this blog, part of the reason was because I was doing is because after the financial meltdown  it confirmed to me that making my own decisions was the best way to do. Sure,  I may miss out on some great runs, but I also haven't lost several BILLION dollars.  The question that keeps coming up is how did they lose so much money? Simple, THEY DIDN'T KNOW WHAT THEY ARE DOING!

First, here's the Cliff Notes version of what happened when the whole financial world went crazy:

  1. People were being given fixed and adjustable rate mortgages they absolutely could not afford (yours truly included). In some cases, the person getting the mortgage didn't have to verify that they even had a job.  They figured they could always sell the house at a higher price and make money. Remember all those house flipping shows on A&E on Saturday mornings?
  2. Because so much money was so easily available, housing prices kept increasing. This is what was known as the housing bubble. (um, bubbles pop..)
  3. These mortgages were grouped together and sold to investors as a big block of A-rated assets. Why?  Because the rating agencies and the financial institutions selling them did not actually look at the individual mortgages that were making up the blocks. They kinda sorta took each other's word that it was all good.  They then borrowed money, using these "assets" as collateral.
  4. It's more complicated, but some people looked into the blocks and realized what a mucking fess they were. They then made bets against the assets, realizing they were eventually going to blow up. It got so crazy that some fund managers were having blocks put together that were as bad as they could make them, sell them to their clients, then bet against the same block they told their clients were rock solid. These were all still getting A-ratings.
  5. Eventually, when the adjustable mortgages reset to their final rate the mortgage payments shot up, much higher than the mortgagee could afford. And the fixed rate mortgagees couldn't sell the house they shouldn't have bought anyway, nor could they afford the payments. As a result, a few new things happened:
  • Housing prices stopped rising because there were no new people to get ridiculous mortgages.  For more info, take a look at Tulipmania.
  • Mortgagees started defaulting like crazy because they couldn't afford the payments.
  • Because the mortgages started defaulting, the blocks of mortgages lost value.  Remember these blocks were used as collateral for loans. If suddenly you don't have collateral, your loan can get called in. If you don't have the money to replace the lost value, screwed is an understatement. By the time the mortgages were defaulting and taking the investors with them, Wall Street had been buying each other's crappy crap crap, so when one went over the cliff, they were all handcuffed together and they all went.


That's the truly Cliff Noted version of the mess.  For a more detailed and entertaining summary, read Michael Lewis's The Big Short: Inside The Doomsday Machine.  I recently heard Mr. Lewis in an interview on NPRs Wait Wait Don't Tell Me game show. The one thing he reiterated is that Wall Street still doesn't have a clue. (Read his book Liar's Poker for a more in depth discussion of Wall Street's cluelessness.)

I guess the long overdue point I'm making is, why would anyone blindly trust their future to an industry that does not have anywhere near your best interest at heart and take their fees up front whether they actually make you money or not?  Trust me, investing in stocks and bonds is not rocket science  So long as they make you believe 1) it's too hard to do on your own and 2) they know what they're talking about, they have you.

Before I get beat up, I have no ax to grind with financial advisors or investment bankers. I just think that those "experts" on Wall Street that almost destroyed the economy of the planet are probably as collectively stupid as they appear.

As for me, my portfolio has been on a roll as of late.   My return has doubled in the last month. Still looking at Fanny Mae and Freddie Mac, they're still under $.30 a share so I'm still watching it.

Monday, September 20, 2010

The Recovery

Since my last post, I've done pretty well, actually more than doubled my gains. Still, I'm bearing on "the market" even if "my market" is doing great. Today the market stands about 10,700. I still think it will hit 10,000 before 11,000. Why? I just see this market as still pretty skiddish. I got rid of Freddie Mac (FMCC.OB) & Fannie Mae (FNMA.OB) and they are still tanking. I still plan to jump back into them when they look like they're going to recover.


 A few months back, the markets went buck nutty because of the collapse of the Greek economy. While I still don't know why my stocks got hit because of it, there is a very good NPR podcast called Planet Money that explains exactly what mess Greece got itself into.


The problem I will have soon if this market keeps going like it is, is when do I get out?  Here's my holdings and current gains & losses.

AAPL 163.44%
AET -0.13%
AGP 34.75%
AIG -1.74%
AXP 219.72%
BP 0.39%
COF -0.23%
DIS 35.97%
EBAY 16.08%
F 194.85%
JBLU 2.44%
LF -5.06%
LVLT -19.69%
MA 30.99%
PG -6.61%
SBUX 30.60%
SIRI 1.74%
TJX -4.53%
TM -6.46%
XRX 53.03%


I'm approaching my alltime high in dollars  and will start paring down soon. Stay tuned...

Monday, August 30, 2010

Bye Bye Banks

I got out of some of my banks and a telecom today, Citigroup (C), Bank of America (BAC) and Research In Motion (RIMM). They were killing my returns. I think the banks will rise at some point, but I think they will continue to fall until at least 1Q11 (first quarter 2011). As for RIMM, unless they got an answer to the iPhone, they're toast in the long term. And it's getting warm...

And looking at my holdings, I'll be pulling out of more stuff tomorrow. The "market" is hovering around 10,000. It dropped 140 points today, the big loser was Frontier Financial (FTBK.PK), losing 25% today on absolutely no good or bad news. I think the Dow will hit 9,000 before 11,000. Why? Because it is having a heck of a time holding itself above 10,000 and the economy is still stalled. Businesses aren't hiring (trust me, I know). The market has tried to lift itself for the past 6 months, but it can't sustain it. Therefore, I think 10,000 is an artificial level and it will slowly drift down over the next 4-6 months. Given that, I think some of my good holdings might have to be cut. Ironically, I'm only down 8% in AIG (AIG), the one who started this mess.

Wednesday, August 25, 2010

Run For the Hills!

Another bad day in StockMarketVille. The Dow lost 133 points, due to a huge drop in home sales, ie, "..nobody bought houses last month, I better sell all my stocks!". My big loser was Web Media Brands (WEBM), who lost 10% yesterday, they announced financials a week ago - apparently it took everyone a week to read them. They did announce a smartphone games summit yesterday. I guess nobody wants to go. No, I don't see a correlation between smartphones and home sales either.

As we get toward the end of the year, I think mutual fund managers will start trying to clean up their holdings so when they report out in December they don't have all that crap they been losing money on all year on their books. That and the housing news will make for an ugly time ahead, at least until the mid term elections in November. In my logic, that will put downward pressure across the board. I see the downside a higher likelihood than the upside, at least for a few months. I'm not going to sell everything, but I'm going to take a good hard look at RIM, Yahoo and a few of the bank stocks I'm holding and been getting my butt kicked on. I'm not making any predictions on what I think these companies will do, but I don't see their stocks going anywhere positive for a while. I think/hope today will make a bit of a recovery since the market has been dropping for a few days. But I don't think it will last, so I'm going to actually try to time the market this time. OK, let's be honest, we all do that but don't call it that.

Thursday, August 19, 2010

He Giveth and He Taketh

As good as the last few days were, today is worse. "The Market" is currently down about 156 points, but so are about 90% of the stocks I follow. It ended losing 144 points for the day. The "experts" are saying it's because jobless claims were announced to day and are higher than expected. Apparently, most of the people who are trading stocks (Ma and Pa Public) are sitting around waiting for bad or good news and making their immediate trading decisions based on what they hear. Here's a new one: The Hindenberg Omen! I guess if you frequently cry doom and gloom, eventually you will be right.

The big loser on my watch list is Frontier Financial (FTBK.PK) who lost 20% today. No headlines so I can't tell you what was behind it. They were followed by Motors Liquidators (MTLQQ.PK), that quasi company that sorta kinda owns GM (article), down 14.8% for the day. Bummer news since yesterday they announced they were going to push for an initial public stock offering. I haven't decided if I would buy GM in their IPO. Chances are, if you can get in good the first few days you'll make out like a bandit on speculation, just not sure if I believe they've turned themselves around sufficiently to warrant any long term consideration.

Wednesday, August 18, 2010

Fannie & Freddie and GM wants us to buy it, again

Wow. AFont sizeuthentidate Holdings (ADAT), yesterday's big winner, is down 11.6% today. And still no headlines. This is a perfect example of the illogic of the stock market. Freddie Mac & Fannie Mae both got waxed. Probably had to do with "NEW YORK (Reuters) - The four largest U.S. banks could face as much as $42 billion in losses as they repurchase faulty mortgages from housing finance giants Fannie Mae and Freddie Mac, Fitch Ratings said on Wednesday." At least this time there was really something for the market to react to.

GM filed paperwork for an initial public offering today, meaning we'll be able to buy ownership shares in the company we bought last year. I have mixed feelings about GM. I think if they go back public, in the short run at least the stock will jump. But I haven't yet seen that they are doing anything different than what they've done the last 30 years which got them into this mess in the first place.

Read an interesting article about Google. They are up almost 389% since they went public 6 years ago, but they are down 20% YTD. That means if you bought Google on January 1, 2010, you have lost 20% - on the Google! The same company that is selling Andriod cell phones all over the place. I guess the point is you can't invest in the popular companies at the wrong time.

Tuesday, August 17, 2010

Back in the saddle

My apologies to the few of you reading this. Job search has been taking all my time the last few weeks. No excuse, I need to keep writing and I will definitely try harder. Now, let's look at today's market. It's 3:05 and "the market" is up 154 points. Big whoop, what's really important to me is that my holdings are up 1.4% for the day. USAToday says that the markets are up due to rising home sales. Soooooo, because your neighbors are buying houses, you buy stocks. Sorry, that doesn't make sense to me. As time goes on, I'm thinking more and more stock transactions are computer initiated, if stock X goes up, then buy stock Y. The article also said people are encouraged by higher earnings are The Home Depot (HD) and Walmart (WMT). Here's my unbelief, for this all to be true, 100 million investors would have to be glued to their TVs looking at housing starts and big name company earnings and immediately making the decision either buy or sell a bunch of stocks all over the place.

Earlier today Authentidate Holding Corp (ADAT) was up 12% for the day. It's now up just over 2%. What was the big news that caused this spike in this company with a market capitalization of $30 million? Beats me. According to Yahoo they haven't had a headline in 12 days. They have an earnings announcement in September. But they did get a new PR firm a few weeks back. I guess it's working. As I'm writing this, it's back up 11%. My guess is that when some other stock moved some computer algorithm said buy a poopload of ADAT, now sell it, now buy it again. Seriously, imagine the people who work there and maybe have their 401ks wrapped up in this company's stock. They must be going batpoop today.

Netflix (NFLX) is down 2% today, the only news I see is that HBO is going to the iPad and not to Netflix. Theroretically, 2% of the value of Netfilx was due to an impending HBO distribution deal. Um, yeah, right. Frontier Financial got a 13% haircut today. Why? Beats me. The last headline was June 9 about a shareholder lawsuit. My point is, if it was news driving this stock down 13%, we'd know. It's not people, it's Skynet....
Oh yeah, still following Fannie Mae and Freddie Mac. They're still in the $.40 range. Haven't repulled the buy trigger yet. I think they may shrink a little more.

Wednesday, August 4, 2010

The Return of Moe

Hey, I didn't post in July, the job search has been taking all my time. I'm still out of Fannie Mae and Freddie Mac, waiting for them to finally bottom out. I still think they are great long term plays as the government still backs them.

Haven't bought or sold anything over the past 4 weeks, my returns are finally starting to look decent again. I think in general "the market" has probably bottomed out and now is a good time to snag bargains, then again, it's always a good time to snag bargains. It was a gamble, but as of today I'm still up 2% in BP (BP). I am going to keep my eye on RIM, they got smacked down today. Maybe someone besides Priceline (up 22%) had a good day, but in general the market seems to be blah today. For all the hoopla about Android phones, the Google's stock isn't moving.